What every contractor should know about unsecured home improvement loans
When homeowners start researching financing options, unsecured home improvement loans are often one of the first topics they encounter. That’s because many homeowners want a way to finance a project without using their home or other assets as collateral.
For contractors, understanding how unsecured financing works can make financing conversations easier. It can help you address common concerns, explain the benefits clearly, and show homeowners how financing may help them move forward with projects they want or need.
What is an unsecured home improvement loan?
An unsecured home improvement loan is a loan that does not require collateral. Homeowners do not have to pledge their home, vehicle, or other assets to apply. Instead, approval is generally based on creditworthiness and other financial qualifications.
This is one reason unsecured financing appeals to many homeowners. They can explore financing options without putting their home equity or personal assets on the line.
For contractors, that simplicity can remove a common obstacle during the sales process. Rather than discussing liens, collateral, or home equity requirements, you can focus on the project value and the homeowner’s available payment options.
How does approval typically work?
Most unsecured loan approvals are driven primarily by the applicant’s credit profile and overall financial picture. Lenders may consider credit history, credit score, debt-to-income ratio, and other factors that can affect their ability to repay the loan.
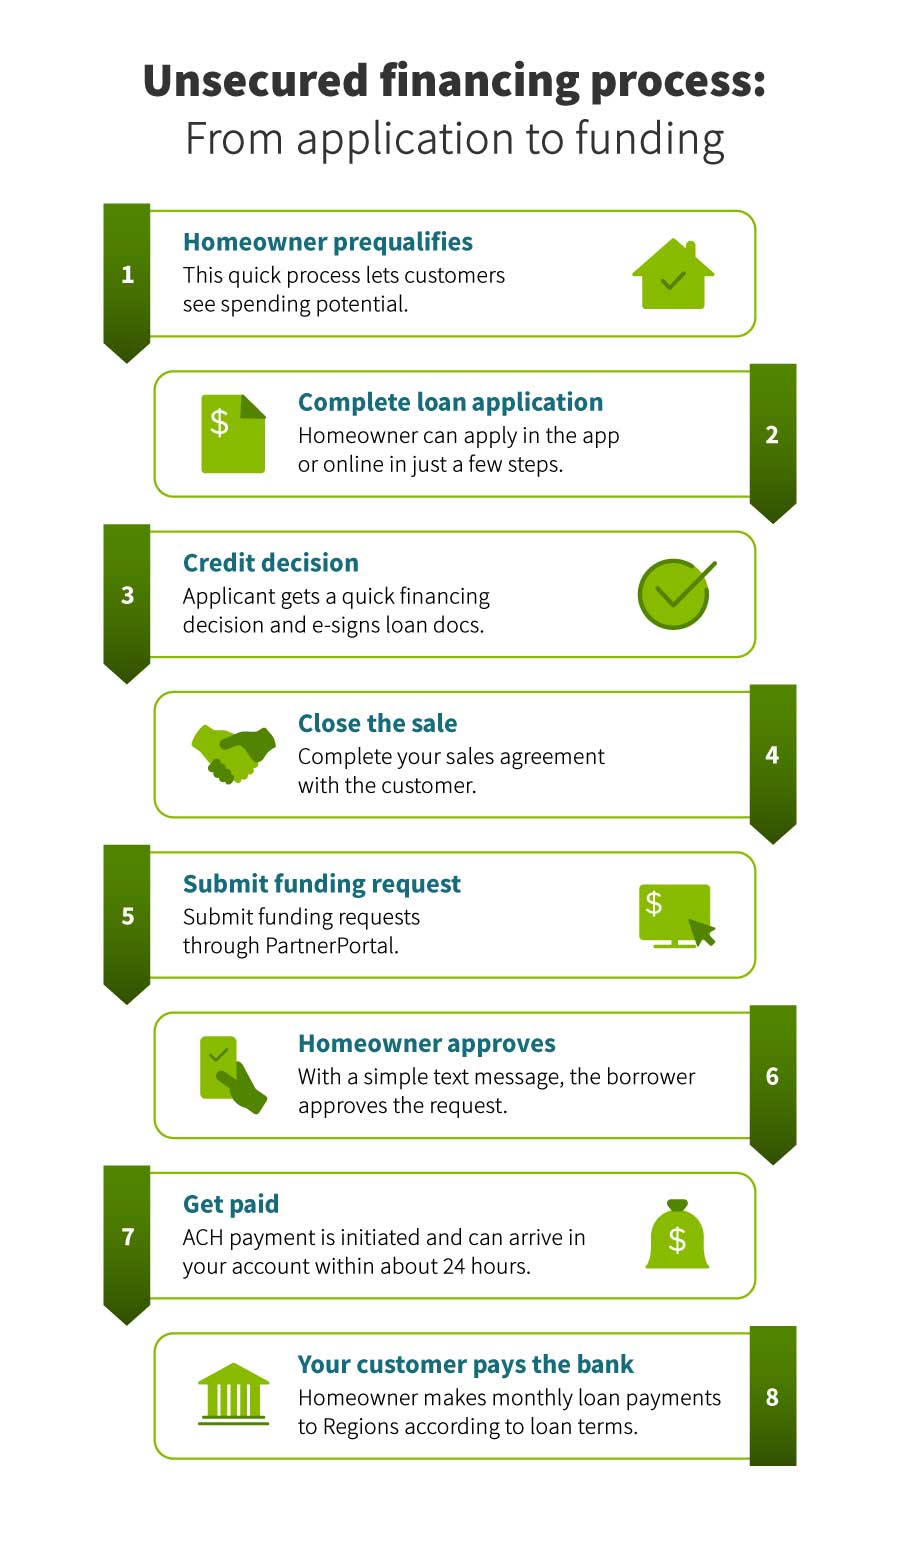
Regions Home Improvement Financing offers a simple prequalification that uses a soft credit pull. This lets homeowners explore potential financing options and establish a realistic project budget without impacting their credit score.
If the homeowner decides to proceed, the full loan application includes a hard credit inquiry as part of the underwriting process. For many contractors, prequalification can be a useful conversation starter because homeowners may be more comfortable discussing financing when they know they can first explore potential options without immediately affecting their credit.
Why do homeowners choose unsecured financing?
Unsecured financing can offer several advantages that homeowners often value when planning a home improvement project.
- No collateral required
Because unsecured loans don’t require collateral, homeowners can explore financing options without pledging their home or other assets. This can help ease homeowner concerns. - Simple paperless applications
Regions Home Improvement Financing offers simple paperless loan applications that can help streamline the financing process. Rather than managing paperwork, many homeowners can complete the application process electronically. - Fast path from approval to project start
Once a loan is approved, Regions Home Improvement Financing pays funds directly to you, the contractor, helping projects move forward quicker and giving you better control over your cash flow. Homeowners can approve your funding requests electronically through text-based notifications. After approval, distributions typically arrive in your account via ACH in about 24 hours.
What projects can be financed with unsecured loans?
Common projects include HVAC replacement and upgrades, roofing and siding projects, window replacement, kitchen and bath renovations, decks, fencing, foundation repair, outdoor living projects, and dozens of other home renovation categories.
How can unsecured financing benefit contractors?
Financing conversations are not just about helping homeowners. They can also support your business goals. When customers understand monthly payment options, budget conversations may become more productive. Offering financing can help homeowners move forward sooner, and improve the overall customer experience. Additionally, offering financing can improve your sales numbers — such as 33% bigger jobs.
- You get paid directly
With Regions Home Improvement Financing, approved loan funds are distributed directly to you, the contractor. - Non-recourse funding provides additional certainty
One feature many contractors appreciate is the non-recourse nature of these loans. Once Regions Home Improvement Financing has paid you, those funds are not clawed back if the homeowner later falls behind on payments to the bank.
Common homeowner concerns and how to address them
Homeowners may ask whether they must use their home as collateral, whether applying affects credit, how the contractor gets paid, and whether home equity is required. Clear explanations can build confidence and help homeowners feel more comfortable with moving forward on their project.
How to position unsecured financing in the sales process
The best financing conversations begin with education rather than a sales pitch. Focus on the ability to prequalify using a soft credit inquiry, the convenience of paperless applications and quick electronic approvals, lack of collateral requirements, direct contractor funding, and flexible loan choices.
The bottom line
Unsecured home improvement loans continue to attract homeowner interest because they offer a straightforward path to financing without requiring collateral. For contractors, understanding how these loans work can make financing conversations more productive and help homeowners feel more confident in their decisions.
Customers may think credit cards make sense for some projects, especially when promotional financing is available, but unsecured home improvement financing also can feature promotional rates, including same-as-cash terms.
If you’re ready to start offering financing choices to your home improvement customers, or look into making the switch to Regions Home Improvement Financing, visit this page.
Related Insights
-
 Article
8 min read
-
Article
12 min read
-
Article
7 min read
-
 Calculator